Building Generational Wealth: Rich vs Really Rich
February 8, 2024 · Alexander Whaley
The richest-looking person in the room is rarely the wealthiest. And that distinction — between high income with high spending and moderate income with high net worth — is the single most important thing to understand about building wealth that lasts beyond your lifetime.
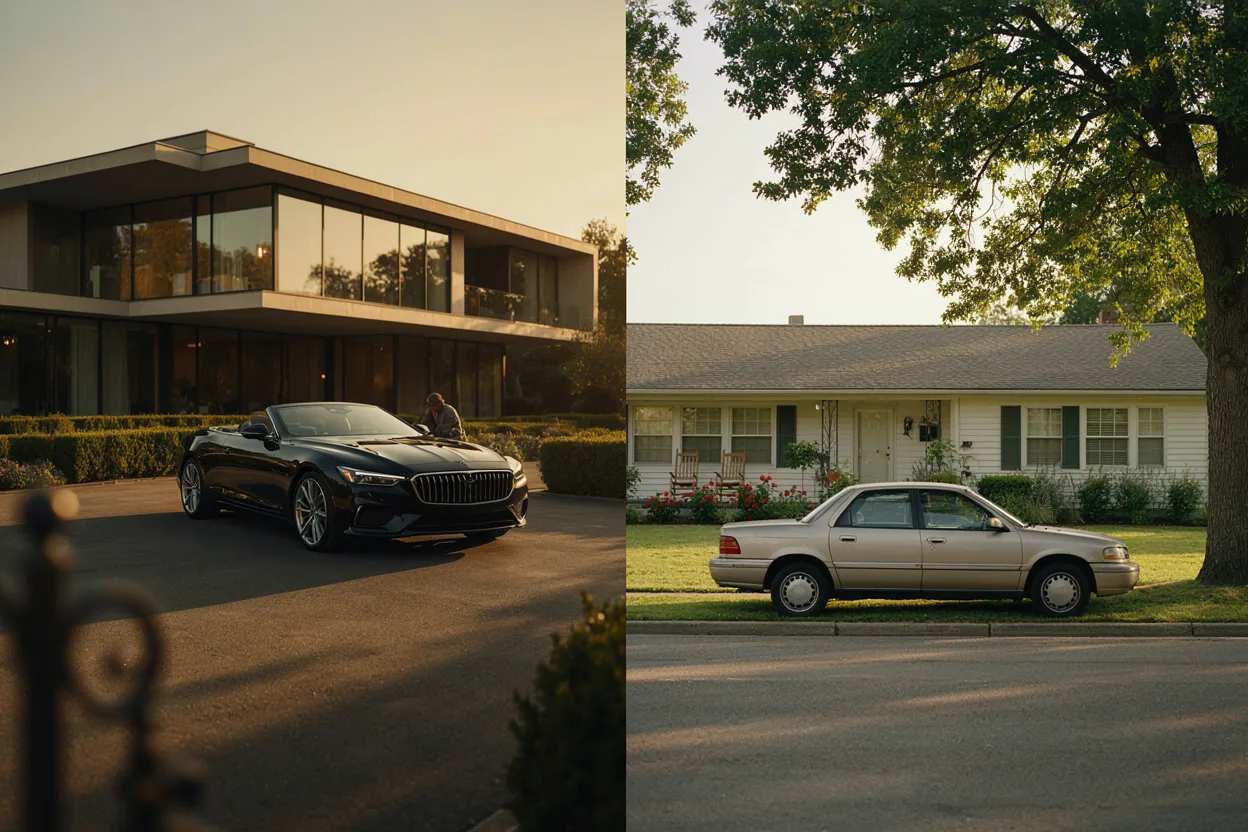
Thomas Stanley and William Danko spent twenty years studying millionaires for their book The Millionaire Next Door. What they found surprised them: the typical American millionaire didn’t drive a Mercedes, didn’t wear a Rolex, and didn’t live in a gated community. They lived in modest neighbourhoods, drove domestic cars, and had accumulated wealth by spending significantly less than they earned. The people who looked richest — the ones with the luxury cars and designer clothes — were often the ones with the highest debt and the lowest net worth relative to their income.
That gap is the difference between being rich and being truly wealthy. And understanding it changes everything about how you build, protect, and transfer wealth across generations.
What “rich” actually means — and why it’s a trap
Being rich means having a high income. Being wealthy means having a high net worth. The two are not the same thing, and confusing them is the most expensive mistake in personal finance.
A person earning $250,000 a year who spends $240,000 is rich — they have a high income, a visible lifestyle, and all the material markers of success. They’re also $10,000 away from financial fragility. One bad quarter, one unexpected medical bill, one job loss, and the lifestyle collapses. That’s not wealth. That’s high-speed financial fragility wearing expensive clothes.
A person earning $85,000 a year who spends $60,000 and invests the rest is building wealth. They may drive a ten-year-old car and live in a house that doesn’t photograph well for Instagram. But their net worth is growing every month, their investments are compounding, and they have a financial cushion that can absorb almost anything life throws at them.
The Federal Reserve’s Survey of Consumer Finances documents this pattern clearly. Among households in the top 10% of income, a significant minority have net worth below $500,000 — meaning they earn a lot but haven’t converted that income into lasting assets. Meanwhile, many households in the top 10% of net worth have incomes well below $200,000 — they accumulated wealth through decades of spending less than they earned and investing the difference consistently.
| Metric | Rich (high income, high spending) | Wealthy (moderate income, high net worth) |
|---|---|---|
| Annual income | $200,000–$500,000+ | $80,000–$200,000 |
| Annual spending | $180,000–$450,000+ (lifestyle matches income) | $50,000–$120,000 (well below income) |
| Savings rate | 5–15% | 25–40% |
| Net worth trajectory | Growing slowly or flat (spending eats most gains) | Compounding steadily (investments grow on top of investments) |
| Visible wealth | High — luxury car, big house, designer brands | Low — modest home, reliable car, no visible brands |
| Financial fragility | High — one job loss or medical event away from crisis | Low — can sustain lifestyle for years without new income |
| Generational transfer potential | Low — most assets are consumed, not transferred | High — accumulated assets pass to next generation |
The pattern is consistent across Stanley’s research, across the Federal Reserve data, and across every wealth study I’ve read: the people who look richest are often the least wealthy, and the people who are wealthiest often look the most ordinary.
Why generational wealth usually doesn’t survive three generations
There’s an old proverb — “shirtsleeves to shirtsleeves in three generations” — that describes the most common pattern in family wealth. The first generation builds it, the second maintains it, the third spends it. And the research confirms it’s not just a saying — it’s a documented pattern.
Studies by the Williams Group wealth consultancy, cited across Federal Reserve wealth research, found that roughly 70% of family wealth is lost by the second generation, and 90% is gone by the third. The reasons aren’t what most people assume — it’s not bad investments or market crashes. It’s a combination of three things: family communication failures, unprepared heirs, and a lack of shared mission.
The first generation built the wealth through discipline, frugality, and long-term thinking. They know what it cost. The second generation grew up with the wealth but didn’t build it — they understand it exists but don’t fully grasp the behaviours that created it. By the third generation, the wealth is a given — like oxygen, like gravity — and the behaviours that built it feel irrelevant or restrictive.
This is where Dottie’s still-figuring-out question applies directly: can money psychology actually change? The evidence from generational wealth studies suggests that financial behaviours are learned, not inherited. The first generation’s discipline doesn’t pass to their children automatically — it has to be actively taught, modelled, and reinforced. Families that successfully transfer wealth across multiple generations almost always do three things: they talk openly about money, they involve heirs in financial decisions early, and they establish shared family values around wealth that go beyond the money itself.
| Why it fails (70% of families) | What successful families do (30%) | The mechanism |
|---|---|---|
| No family communication about money | Regular, age-appropriate money conversations from childhood | Heirs learn the values and behaviours, not just the numbers |
| Heirs unprepared for wealth management | Heirs involved in financial decisions progressively | By the time they inherit, they’ve already managed real money |
| No shared family mission or values | Written family mission statement about wealth’s purpose | Wealth has a “why” beyond accumulation — a purpose that outlasts the founder |
| Wealth treated as individual, not collective | Family governance structure (trusts, councils, regular meetings) | Wealth becomes a shared responsibility, not a personal entitlement |
| Lifestyle inflation with each generation | Spending rules tied to income from assets, not asset liquidation | The principal is protected; only the growth funds lifestyle |
The behaviours that actually build generational wealth
Building wealth that survives beyond your lifetime isn’t about finding the perfect investment or hitting a home run. It’s about consistent, boring behaviours repeated over decades — and then teaching those behaviours to the next generation.
Gerd Gigerenzer’s research on simple heuristics applies here in a way most wealth-building advice misses. The elaborate strategies — tax-loss harvesting, alternative investments, complex trust structures — get the attention. But the simple rules outperform them for most families over most time horizons. Spend less than you earn. Invest the difference in diversified index funds. Don’t interrupt the compounding. That’s it. That’s the strategy that builds millionaires in Stanley’s research, and it’s the strategy that builds generational wealth.
The complexity comes later — when you’re thinking about estate planning, tax-efficient transfers, trust structures, and family governance. But the foundation is always the same: consistent saving, consistent investing, and consistent spending discipline over a long period.
| Phase | What to do | Timeline | Why it works | What most people get wrong |
|---|---|---|---|---|
| 1. Accumulate | Spend less than you earn. Invest the difference in diversified, low-cost index funds. Do this every month for 20–30 years. | Ages 25–55 | Compound growth turns consistent contributions into substantial wealth | People try to time the market, pick stocks, or chase returns instead of being consistent |
| 2. Protect | Establish estate plans, trusts, and insurance. Document your financial values and wishes. | Ages 45–65 | Wealth without a plan is wealth that dissipates after you’re gone | People delay estate planning because it feels morbid or unnecessary |
| 3. Transfer | Begin transferring wealth during your lifetime — not just at death. Involve heirs in decisions. Teach the behaviours. | Ages 55–75+ | Heirs who learn while you’re alive are prepared; heirs who inherit without preparation spend | People wait until death to transfer, leaving heirs unprepared and overwhelmed |
| 4. Sustain | Family governance: regular meetings, shared mission, spending rules tied to investment income. | Ongoing, across generations | Structure preserves what discipline built; without structure, entropy wins | Families skip governance because it feels corporate or unnecessary for “our family” |
Rich vs. wealthy across life stages — what changes and what stays the same
The rich-vs.-wealthy distinction plays out differently depending on where you are in life — but the underlying mechanism (spend less than you earn, invest the difference) stays the same at every stage.
| Life stage | What “rich” looks like | What “wealthy” looks like | Key decision that separates them |
|---|---|---|---|
| 20s | New car financed at 7%, apartment in the trendy neighbourhood, $400/month on clothes and dining | Used car paid in cash, modest apartment, $500/month into a Roth IRA | Lifestyle inflation vs. early investment — the 20s decision that compounds for 40 years |
| 30s | Bigger house, two car payments, private school, lifestyle that requires both incomes | Modest house with a 15-year mortgage, one car paid off, maxing retirement accounts | Housing cost — the single largest expense that determines whether you build or consume wealth |
| 40s | Peak earning years spent on lifestyle upgrades — boats, renovations, luxury travel | Peak earning years spent on accelerated investing — catch-up contributions, taxable brokerage | What you do with raises — lifestyle creep vs. savings rate increases |
| 50s | “We’ve earned this” spending — justifying luxury as reward for decades of work | Downsizing, consolidating, simplifying — preparing wealth for transfer | Estate planning — whether you start thinking about transfer or keep consuming |
| 60s+ | Spending down assets to maintain pre-retirement lifestyle | Living on investment income, principal intact for the next generation | Withdrawal strategy — spending principal vs. spending only investment income |
The pattern at every stage is the same: the “rich” choice is the one that looks good now. The “wealthy” choice is the one that builds something that lasts. The difference isn’t intelligence or income — it’s whether you’re optimising for this year’s Instagram feed or for your grandchildren’s financial security.
The thing most wealth advice gets wrong about “rich”
The standard framing — rich is bad, wealthy is good — is too simple. There’s nothing wrong with enjoying the money you earn. The problem isn’t spending. It’s spending that prevents you from building something that outlasts you.
This is where the usual personal finance advice breaks down. The “latte factor” framing — that your daily coffee is keeping you poor — is nonsense. A $5 coffee every day for 40 years, invested instead, would grow to roughly $120,000. That’s meaningful, but it’s not the difference between rich and wealthy. The difference is in the big decisions: housing, transportation, and whether your spending grows every time your income does.
The Federal Reserve’s Survey of Consumer Finances shows that the top driver of net worth differences isn’t income — it’s the savings rate. A household earning $100,000 with a 30% savings rate will accumulate more wealth over 25 years than a household earning $200,000 with a 5% savings rate. The math is straightforward: $30,000 a year invested at 7% for 25 years is roughly $1.9 million. $10,000 a year at the same rate is roughly $630,000. The higher-income household has three times the income but a third of the wealth.
The practical implication: if you want to build generational wealth, the single most impactful decision you can make is to keep your spending flat while your income grows. Every raise that goes to investments instead of lifestyle is a decision your grandchildren will benefit from. Every raise that goes to a bigger house or a newer car is a decision that keeps your family one generation away from shirtsleeves.
Frequently asked questions
What is the difference between being rich and being wealthy?
Being rich means having a high income, often accompanied by high spending and visible lifestyle markers. Being wealthy means having a high net worth — assets that exceed liabilities, built through consistent saving and investing over time. Thomas Stanley’s research in The Millionaire Next Door showed that most actual millionaires live modestly, while many high-income earners have relatively low net worth.
Why does generational wealth usually disappear by the third generation?
A U.S. Trust study found that 70% of family wealth is lost by the second generation and 90% by the third — primarily due to family communication failures, unprepared heirs, and a lack of shared mission about the wealth’s purpose. The wealth-building behaviours aren’t inherited; they have to be actively taught and reinforced.
What is the most important behaviour for building generational wealth?
Keeping spending flat while income grows — every raise that goes to investments instead of lifestyle compounds over decades. The Federal Reserve’s Survey of Consumer Finances shows that savings rate, not income level, is the top driver of net worth differences between households.
Can you enjoy your money and still build generational wealth?
Yes — the problem isn’t spending, it’s spending that prevents wealth accumulation. A family that spends 60% of their income and invests 30% is building generational wealth while still enjoying life. The distinction is between spending that’s funded by investment income and spending that prevents investment income from growing.
When should you start thinking about estate planning and wealth transfer?
Estate planning should begin in your 40s–50s, but wealth transfer education should start much earlier — involving children in age-appropriate financial conversations from childhood and progressively including them in real financial decisions. Families that successfully transfer wealth across generations begin the education process decades before the actual transfer occurs.
Is the “shirtsleeves to shirtsleeves” pattern inevitable?
No — roughly 30% of families successfully maintain wealth across three or more generations. The common factors are open family communication about money, progressive involvement of heirs in financial decisions, a written family mission statement about wealth’s purpose, and governance structures that protect the principal while allowing investment income to fund lifestyle.